Global Precision Motion Stages Market Expands with Semiconductor Inspection, Nanopositioning and Ultra-Precision Automation Demand Through 2032
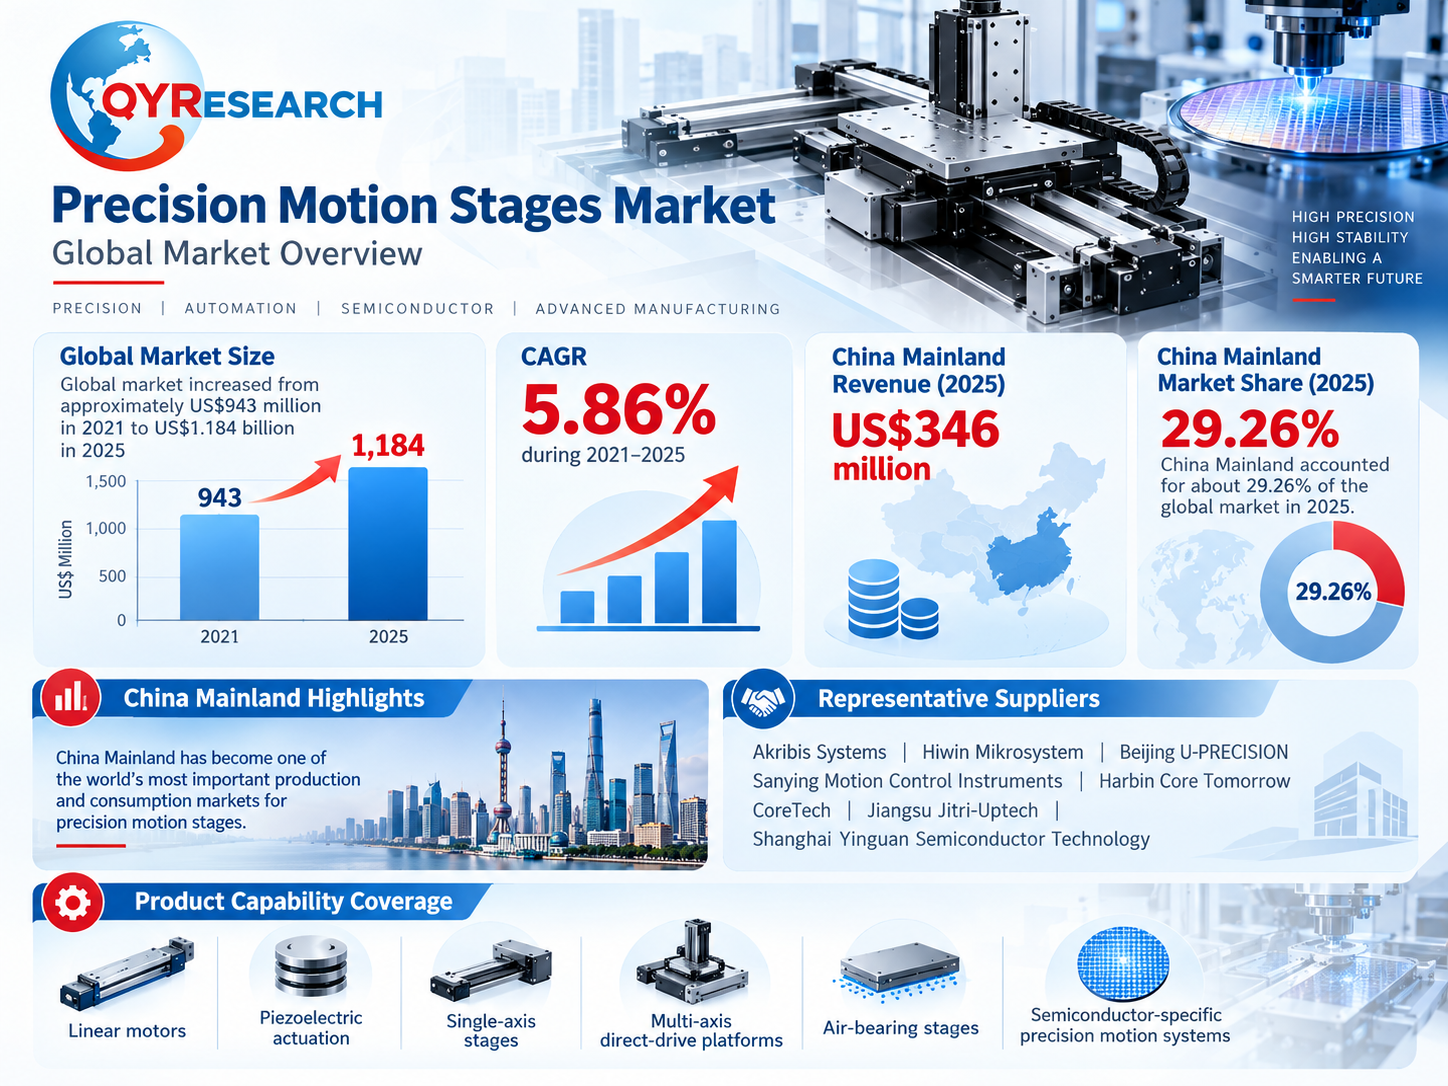
PUNE, MAHARASHTRA, INDIA, October 12, 2026 /EINPresswire.com/ — Pune, India: According to QYResearch, the global Precision Motion Stages market expanded from approximately US$943 million in 2021 to US$1.184 billion in 2025, representing a CAGR of approximately 5.86%. The market is projected to reach approximately US$1.291 billion in 2026 and US$2.098 billion by 2032, corresponding to a forecast CAGR of about 8.43% during 2026–2032. The acceleration reflects a transition from predominantly cyclical equipment demand toward structurally higher system value as motion platforms incorporate additional axes, higher-end bearings, sophisticated feedback devices, software, calibration and application-specific engineering.
Download Exclusive Research Report PDF Sample: (Including Full TOC, List of Tables & Figures, Chart) @ https://qyresearch.in/request-sample/chemical-material-global-precision-motion-stages-market-share-and-ranking-overall-sales-and-demand-forecast-2026-2032
Why This Market Matters:
Precision motion stages occupy an enabling position across semiconductor manufacturing, wafer inspection and metrology, advanced packaging, photonics, FPD production, laser micromachining, precision measurement, biomedical instrumentation and research equipment. In electronics and semiconductor applications alone, motion systems are required in wafer inspection, exposure and lithography-related equipment, probe stations, wafer bonding, handling, alignment and packaging processes. QYResearch estimates that electronics and semiconductors represented approximately 42.00% of global Precision Motion Stages revenue in 2025 and could increase to 49.75% by 2032, with this application segment projected to expand at approximately 11.24% CAGR during 2026–2032.
Why Companies Are Investing in Precision Motion Systems:
Manufacturers are increasing investment because next-generation equipment needs higher acceleration, lower vibration, better trajectory control, faster settling and more repeatable positioning under real production conditions. AI-related semiconductor infrastructure, advanced packaging and optical communication investment is expanding the need for wafer-processing, testing, inspection and high-precision optical-alignment equipment. The wider semiconductor environment remains supportive: WSTS reported exceptional semiconductor-market expansion in the first half of 2026, driven particularly by artificial-intelligence infrastructure, high-performance computing and advanced memory investment.
Industry Challenges, Technology Solutions and Growth Dynamics
Industry Challenges: The principal engineering challenge is no longer simply reaching a specified static positioning accuracy. Semiconductor, metrology and photonics customers increasingly evaluate dynamic tracking error, settling time, thermal stability, vibration, straightness, flatness, angular error, repeatability, multi-axis synchronization, vacuum compatibility, cleanroom suitability and long-duration reliability. Adding axes also increases calibration complexity, cable disturbance, cross-axis error, heat management and control-system requirements. Meanwhile, suppliers must meet these specifications while reducing machine footprint, integration time and total ownership cost.
Technology Solutions: The industry is responding through direct-drive linear motors, torque motors, high-resolution optical encoders, piezoelectric nanopositioners, crossed-roller bearings, air bearings, magnetic-levitation concepts, integrated planar systems and closed-loop software control. PI, for example, markets linear-motor and air-bearing systems with nanometer-scale encoder resolution and high-speed capabilities, while Aerotech offers linear, rotary, air-bearing and multi-axis positioning architectures for applications including laser processing, metrology and optical alignment. Dover Motion is pursuing greater integration through precision XY platforms with embedded control electronics. These approaches demonstrate how value is moving from a standalone mechanical stage toward an integrated mechatronic system.
Market Driving Growth and Restraint:
Growth is being driven by semiconductor equipment upgrades, AI-related computing investment, advanced packaging, precision inspection, photonic-device assembly, silicon photonics, laser processing, biomedical automation and increasingly sophisticated research instrumentation. The principal restraints remain cyclical capital spending, long equipment-qualification processes, dependence on specialized encoders and control components, high engineering requirements, system customization costs and potential price competition in standard motion products. QYResearch therefore expects the market to expand over the long term while retaining year-to-year sensitivity to semiconductor, display and industrial-equipment investment cycles.
Emerging Trends & Dynamics:
One of the strongest changes is the move from single-axis positioning toward multi-axis and planar motion systems. QYResearch estimates linear stages represented 39.98% of 2025 revenue and multi-axis/planar stages 35.83%; by 2032, their respective shares are projected at approximately 31.64% and 47.42%, which would make multi-axis/planar systems the largest product category by revenue. This does not imply declining linear-stage demand; rather, it indicates faster value growth in XY, XYZ, XYθ, planar-motor, air-bearing and application-specific integrated platforms.
Market Challenges:
Commercial success requires more than a strong datasheet. OEM customers increasingly expect suppliers to demonstrate performance after the motion stage is integrated with payloads, cabling, process forces, temperature variation and machine controls. Customized equipment also creates long qualification cycles and requires sustained application-engineering support. Regional suppliers may compete effectively on price and delivery, while established manufacturers can differentiate through installed base, reliability records, calibration expertise and global service.
Key Business Opportunities:
The highest-value opportunities through 2032 are expected around semiconductor inspection and metrology, advanced packaging, photonics active alignment, silicon-photonics manufacturing, ultra-precision laser processing, automated life-science instrumentation, air-bearing motion, piezoelectric fine positioning and high-performance multi-axis systems. Suppliers capable of combining mechanics, motors, feedback, algorithms and calibration into repeatable production platforms may capture a greater share of equipment value and establish longer-term OEM relationships.
Market Segmentation
By type, the Precision Motion Stages market includes Linear Stages | Rotary Stages | Goniometer/Tip-tilt Stages | Multi-Axis/Planar Stages | Six-DOF/Compound Motion Stages. By axis configuration, the market includes Single-Axis Stages | Multi-Axis Stages. By bearing mechanism, it includes Air Bearing/Magnetic Levitation Stages | Mechanical Bearing Stages. The coexistence of mechanical guides, air bearings, linear motors, piezoelectric drives and other architectures reflects the very different requirements for travel, payload, speed, precision, environment and cost across applications.
By application, the market covers Electronics & Semiconductors | FPD and Optoelectronic | Laser Processing | Precision Measurement | Biomedical | Research/Aerospace & Defense | New Energy Equipment | Others. Electronics and semiconductors remain the dominant growth engine, while FPD/optoelectronics and precision measurement provide substantial complementary demand. QYResearch places their 2025 revenue shares at approximately 14.13% for FPD/optoelectronics and 13.63% for precision metrology, while life sciences, research, laser processing and other applications diversify the market and reduce dependence on a single end-use cycle.
Regional Market Insights
Mainland China has become one of the industry’s most important production and consumption centers. QYResearch estimates 2025 Precision Motion Stages revenue in Mainland China at approximately US$346 million, equal to about 29.26% of global revenue. Its global share is projected to reach approximately 30.58% in 2026 and 36.03% by 2032, implying a regional CAGR of about 11.44% during 2026–2032. Semiconductor equipment localization, advanced packaging, precision inspection, laser processing, new-energy manufacturing and faster local application support are important contributors to this expansion.
North America, Europe and Japan remain strategically significant because of their capabilities in nanopositioning, high-performance metrology, air-bearing scanning, vacuum-compatible motion, photonics alignment and scientific instrumentation. QYResearch projects 2032 global revenue shares of approximately 18.16% for North America, 18.41% for Japan and 14.09% for Europe. South Korea, Taiwan and Southeast Asia are positioned to benefit from semiconductor and electronics manufacturing investment, while India represents a smaller but emerging opportunity as its semiconductor ecosystem expands; India’s Semiconductor Mission highlighted further emphasis in 2026 on design, equipment, fabs, advanced packaging, R&D and talent development. Europe likewise continues semiconductor R&D and capacity initiatives through the Chips Joint Undertaking and related Chips for Europe programs.
Competitive Landscape and Major Global Manufacturers
Competitive Landscape — Key players are investing in: Competition is increasingly centered on multi-axis architectures, direct-drive platforms, air-bearing systems, piezoelectric nanopositioning, high-resolution feedback, thermal management, vacuum/cleanroom compatibility, integrated controllers, calibration software and application engineering. QYResearch estimates that the top five suppliers held approximately 42.72% of global revenue in 2025, while the top ten represented approximately 58.22%, indicating a moderately concentrated market where global technology leaders coexist with specialized regional manufacturers.
Established suppliers retain significant positions in demanding semiconductor, photonics, metrology and research applications. PI provides linear, rotary, air-bearing and nanopositioning technologies; Newport, part of MKS Instruments, maintains a broad photonics and motion-control portfolio; Aerotech supplies single-axis and integrated multi-axis precision motion products; and companies such as ETEL, IKO Nippon Thompson, Kohzu Precision, NSK and other specialists bring differentiated capabilities in direct-drive systems, precision bearings, positioning and machine integration. At the same time, Chinese and Asian manufacturers are expanding from standard stages into linear motors, piezoelectric systems, air-bearing stages and semiconductor-specific multi-axis platforms.
Major global manufacturers include:
MKS Instruments
PI (Hoerbiger)
Sumitomo Heavy Industries
Akribis Systems Pte Ltd
IKO Nippon Thompson
Motion Solutions (Novanta)
Hiwin Mikrosystem Corp
Moog
Cronus
THK Precision
Aerotech
NSK
Schneeberger Group
Beijing U-PRECISION
SmarAct GmbH
Steinmeyer Mechatronik GmbH
Kohzu Precision
Dover Motion
Harbin Core Tomorrow Science and Technology Co., Ltd
CHUO Precision Industrial Co., Ltd
Wuxi CORETECH
Eitzenberger
LAB Motion Systems
Sanying Motion Control Instruments Ltd
ETEL SA
Jiangsu Jitri-uptech
CKD Nikki Denso
Justek
TOYO Automation
PM BV
TRI-N CO., LTD
ALIO Industries (Allient)
Mager Srl
HEPHAIST Co., Ltd
Shanghai Yinguan Semiconductor Technology
Albert (Suzhou) Technology
SURUGA SEIKI Co., Ltd
Wuxi Xivi Technology Co., Ltd
Beijing AUS-PRECISION
PBA Systems Pte Ltd
QYResearch identifies several of these companies among the market’s important global and regional participants, with competitive strengths differing by precision level, actuation technology, environment, application and system-integration capability.
Frequently Asked Questions Answers
(1) What is the expected global Precision Motion Stages market size by 2032?
(2) Which application is expected to generate the strongest demand?
(3) Which product segment offers a major growth opportunity?
(4) What will define competitive advantage through 2032?
Explore Full Report With Detailed TOC Here @ https://qyresearch.in/report-details/6219538/Global-Precision-Motion-Stages-Market
About QYResearch
QYResearch founded in California, USA in 2007. It is a leading global market research and consulting company. With over 19 years’ experience and professional research team in various cities over the world QY Research focuses on management consulting, database and seminar services, IPO consulting (data is widely cited in prospectuses, annual reports and presentations), industry chain research and customized research to help our clients in providing non-linear revenue model and make them successful. We are globally recognized for our expansive portfolio of services, good corporate citizenship, and our strong commitment to sustainability. Up to now, we have cooperated with more than 70,000 clients across five continents. Let’s work closely with you and build a bold and better future.
Contact US
Ankit Jain – Director, Global Digital Marketing
QY Research, INC.
India Office –
315Work Avenue, Raheja Woods, Kalyani Nagar,
Pune, Maharashtra 411006, India
Web – https://www.qyresearch.in
Email- ankit@qyresearch.com
Ankit Jain
QY Research India
+ +91 8149736330
ankit@qyresearch.com
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery